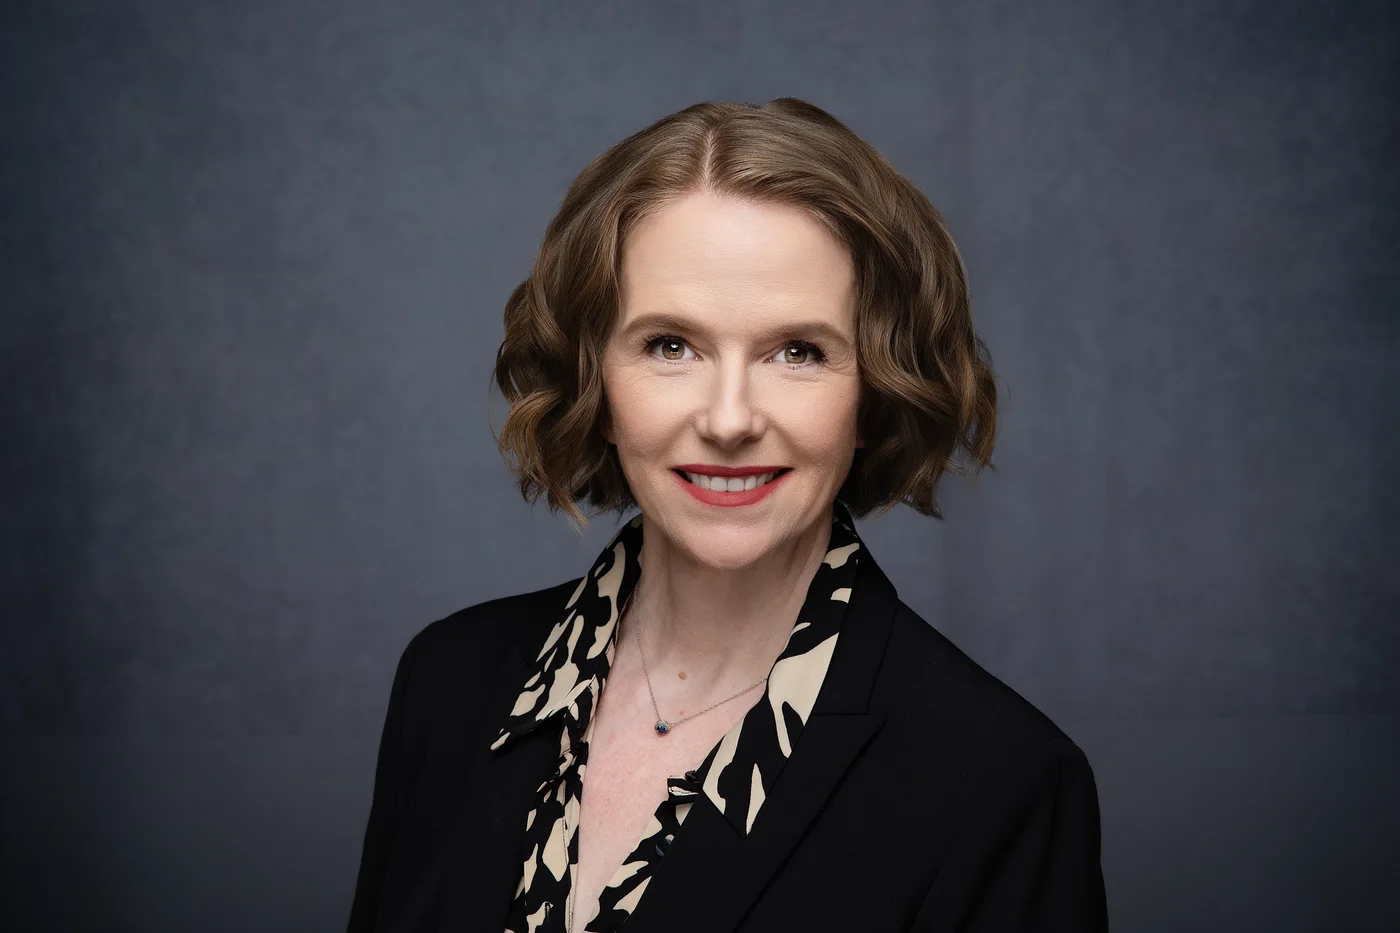
This piece was written by Spencer Lee and featured on National Mortgage News in January 2026. It features commentary from Tela Mathias, managing partner and chief technology officer at PhoenixTeam. The following is a summary of the discussion with attribution to the original reporting. While the first few years of the mortgage industry’s relationship with artificial intelligence have been characterized by new gadgets and fear of missing out, 2026’s themes might center on how companies manage to catch up with its game-changing potential. If or when they do, the industry should start to see standardization and scalability that help it achieve long-talked about, but difficult-to-achieve, ambitions, including greater customer satisfaction, simplified underwriting and faster closings.
People Set the Pace
The businesses that can standardize certain processes with the assistance of AI will set themselves off from the pack, according to technology executives. The first hurdle that needs to be cleared for breakthroughs to happen, though, is to achieve widespread use within an organization.
“What we’re seeing is that it’s the people that are setting the pace. It’s not the tech that’s setting the pace, because there’s this huge gap between what we can actually do with generative AI and how the people are using it, and this gap is only going to grow as models get smarter,” said Tela Mathias, managing partner and chief technology officer at mortgage consultancy firm PhoenixTeam.
“Finding the way that human beings who are ultimately sitting in the chair — engaging with the homeowners, solving problems, uncovering and understanding — and optimizing that relationship with their everyday AI is going to be critical in 2026 because what we’re seeing is that we can eat everything on the buffet,” she added.
The Road to Faster Underwriting and Closings
According to industry executives interviewed for the piece, generative and agentic artificial intelligence are creating noticeable progress toward longtime goals in originations. AI’s improved ability to “read” the full variety of documents needed during underwriting — credit, income, and assets often stored in image or PDF forms — is enabling faster decision-making, clearer eligibility criteria, and shorter turn times across the board.
As development moves forward, borrowers and lenders should plan to start seeing expedited closing times, an aspect of the mortgage experience that has been criticized by customers for years. Artificial intelligence is also helping create a standard for particular documents in a single loan file, a long-sought goal for mortgage development.
What's in Store for Servicing
AI’s capabilities to analyze data quickly and create customized opportunities for the borrower during the origination process likewise carry over to servicing clients and their customers. Newer servicing software easily integrates with AI and other platforms, and the amount of customization that can be applied when working with borrowers is ramping up quickly.
AI’s benefit to servicers appears first and foremost in call centers, where fast analysis of conversation transcriptions and summarization creates savings and better outcomes. The tools are set to get better in 2026.
A Top-Down Approach
The potential won’t translate into results without an all-in approach from companies, Mathias said. Adoption needs to come from the top down to fully understand how game-changing AI is.
“I’ve never seen a technology before where it is so necessary for every level of the organization to have their fingers on the keyboards,” Mathias said. “What I see in 2026 is a much bigger push towards true workforce enablement and really getting under the covers with what it is that we have to do to enable the workforce to take advantage.”